LOSSES FROM SHELLING: HOW ENTERPRISES CAN ACCOUNT FOR DESTROYED PROPERTY FOR TAX PURPOSES
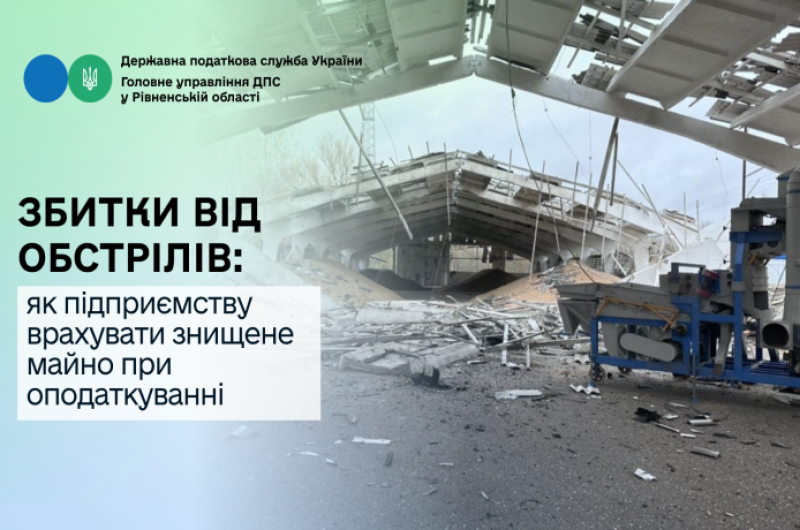
Companies whose property has been damaged or destroyed due to enemy shelling may reduce their corporate income tax base. The rules for writing off such assets depend on the type of property and the enterprise's annual revenue.
Destroyed goods and inventory
The Tax Code does not provide for specific tax adjustments regarding the write-off of destroyed goods or inventory. This means they are written off as expenses in accordance with accounting rules; consequently, the financial result before tax—and thus the corporate income tax base—is reduced.
Destroyed fixed assets (equipment, buildings, vehicles)
In this case, the rules depend on the taxpayer's annual revenue:
• - Revenue of UAH 40 million per year or less: the value of destroyed assets is written off as expenses under accounting rules. These are factored into the financial result before tax and, accordingly, reduce the corporate income tax base.
• - Revenue exceeding UAH 40 million per year (taxpayers subject to tax adjustments): the tax base is reduced by the residual value of the destroyed asset, determined according to tax accounting rules.
•
Note that writing off destroyed goods, inventory, and fixed assets requires proper documentary evidence. The enterprise must conduct an inventory and gather supporting documents that record the fact of such destruction.
These may include a State Emergency Service (SES) report on a fire or destruction, an extract from the Unified Register of Pre-trial Investigations (ERDR) regarding shelling, conclusions from the Chamber of Commerce and Industry, and other documents certifying the fact and causes of the property's destruction.
Further information on tax support mechanisms for affected businesses can be found on the State Tax Service (STS) web portal—specifically in a dedicated information banner regarding support for taxpayers affected by armed aggression.
Hotlines of regional STS offices for businesses that have suffered losses due to the war
Information and inquiry services of the STS Contact Center for war-affected businesses
Force majeure and the destruction of goods: when VAT liabilities are not accrued
Over 11,000 taxpayers have already exercised their right to be exempted from tax obligations due to the consequences of the war
Goods damaged or lost during transport: should compensation be included in a sole proprietor's income? Property destroyed by shelling: how to write off inventory and fixed assets
Lesia Karnaukh: The State Tax Service has prepared a package of tax measures to assist affected businesses
War-damaged property: when real estate tax is not payable
Support for affected businesses: key topic of the meeting between the Head of the State Tax Service and the ACC
Assistance for affected businesses: State Tax Service launches regional hotlines for prompt consultations